Table of contents (28)Show
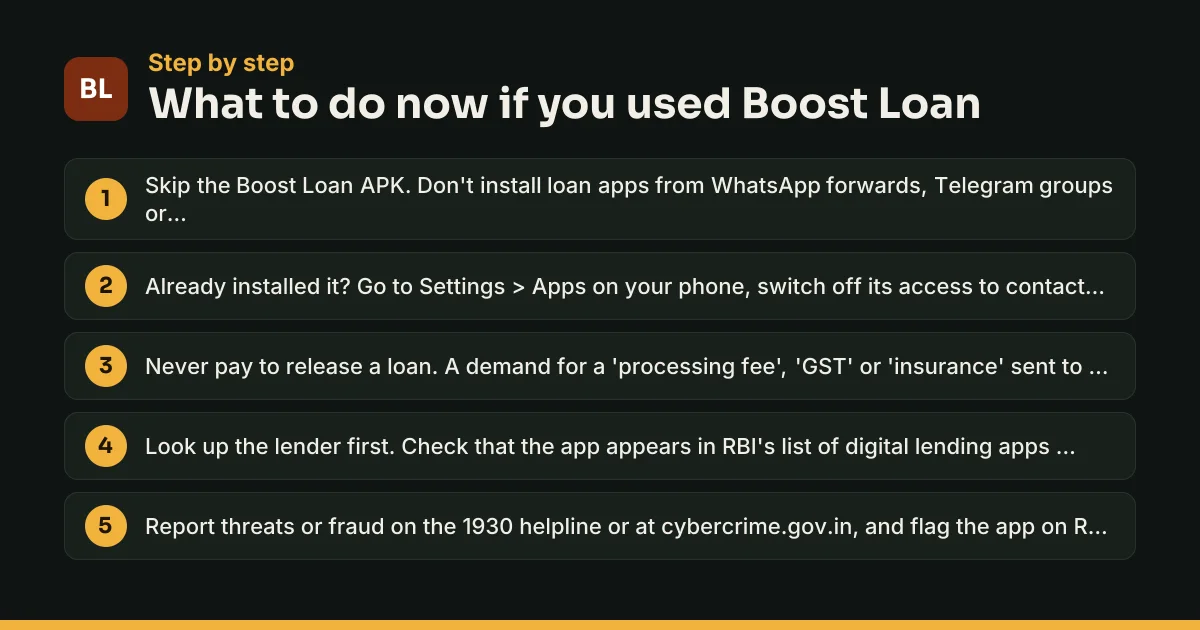
- What to do now
- What we checked about Boost Loan
- Which "Boost Loan" are people searching for?
- Why a free referral code here is a bad deal
- How unauthorised loan apps tend to operate
- What a genuine lending app must show you
- Testing a loan app in five minutes
- Already borrowed through an app like this?
- Regulated loan apps with published referral rules
- Q: Is Boost Loan a real loan company?
- Q: Who lends the money in the Boost Loan app?
- Q: Has RBI approved the Boost Loan app?
- Q: Can I download Boost Loan from Google Play?
- Q: Is Boost Loan the same as MobiKwik Boost?
- Q: Why do some loan apps spread only as APK files?
- Q: What phone permissions should a loan app never need?
- Q: A loan app is threatening to message my contacts. What should I do?
- Q: Can a lender charge me fees that weren't disclosed?
- Q: Why do YouTube videos share Boost Loan referral codes?
- Q: Does a referral code make a loan app any safer?
- Q: What does the person who shares a Boost Loan code get?
- Q: Can a referral code raise my limit on an instant loan app?
- Q: Is it a problem to post my own code for an unregistered loan app?
- Q: What do people mean by a 'Boost Loan APK referral code'?
- Q: Which loan apps have published referral rules?
- Q: Should I take a small loan just to get a referral reward?
- Q: Someone asked for my OTP to 'activate' a referral code. Is that normal?
- Quick FAQs
No app called Boost Loan was listed on Google Play in India when we checked on 15 November 2026, and no bank or NBFC claims it as its lending app, so this page gives no referral code. Without a regulated lender, nobody is accountable for your loan, your KYC documents or the data on your phone, and no referral reward is worth that trade.
That covers every version of the search, from "boost loan referral code free" to "boost loan apk referral code". Below is what we checked, what unauthorised loan apps tend to do, and how to test any lending app before it gets your PAN.
What we checked about Boost Loan
| Check | What we found |
|---|---|
| Google Play, India | Searches for "boost loan", "boost loan app" and "boostloan" showed only other lenders' apps |
| A bank or NBFC naming it | None |
| An older "BOOST LOANS" app | Removed from Google Play on 12 November 2020; its listing no longer loads |
| Official website, grievance officer or address | None we could find |
| Published referral terms | None |
We searched Google Play's Indian store under three spellings, looked for any bank or NBFC that lists an app with this name among its lending partners, and checked app trackers for older listings. Nothing tied the name to a regulated lender.
A legitimate lending app leaves a trail. Its store listing names the NBFC or bank, that lender's website names the app, and RBI's public list shows the two together. Boost Loan didn't pass any of these checks. That doesn't prove a particular app with this name is a fraud, but it does mean you'd be borrowing from someone you can't identify.
Which "Boost Loan" are people searching for?
A loan app passed around as a download link
Searches such as "boost loan apk referral code" suggest many people meet the app as a file to install rather than a store listing. That route skips every check Google Play now runs on lending apps, which is reason enough to stop.
BOOST LOANS, removed in 2020
The only Play Store app we could trace with this exact name, package com.boostme.todayx, was taken down in November 2020, according to the app tracker AppBrain. It can't be installed from Google Play today, and any copy offered elsewhere is unofficial.
MobiKwik's Boost
MobiKwik announced an instant-loan feature called Boost in 2018, built into its wallet app for existing users. It was never a separate app, and we found no referral code linked to it.
Why a free referral code here is a bad deal
People share loan app codes because they earn when you sign up. On a regulated app, that reward is written into published terms and credited inside the app. On an app with no named lender, you can check neither.
What you hand over to make the code work is very real: a PAN, an Aadhaar number, a selfie, your bank details and, often, wide access to your phone. Labels like "free", "today" or "2025" change nothing. Referral codes don't expire daily, and no code changes who's lending to you.
How unauthorised loan apps tend to operate
RBI's caution of December 2020 listed the problems it was hearing about from borrowers:
- Excessive interest rates charged to borrowers.
- Extra charges that were never disclosed at the start.
- Harsh recovery methods that RBI called unacceptable and high-handed.
- Misuse of phone data, collected through the app's permissions.
The same release told the public to check who is behind any online lender and never to hand KYC copies to unverified apps. In December 2025, the government told the Lok Sabha that MeitY had blocked 87 illegal loan apps. A blocked app can be rebuilt under any name, so judge a lending app by the lender behind it, not by its icon.
What a genuine lending app must show you
The lender's name, before you apply
RBI requires platforms lending for a bank or NBFC to name that lender up front. Google Play's personal loan policy for India also makes apps list every partner NBFC and bank in their description.
A Key Fact Statement
Before you sign, a regulated lender gives you a Key Fact Statement with the annual percentage rate, every fee and the cooling-off period, during which you can exit by repaying the principal and the proportionate cost.
Limited access to your phone
Regulated apps can't read your contacts, call logs, files or media. One-time access to the camera, microphone or location is allowed for KYC.
A place on RBI's list
Since 1 July 2025, RBI has published the apps that regulated lenders report to it, as set out in its May 2025 announcement. Google Play then tied its own rules to that list. From 30 October 2025, a new personal loan app couldn't publish in India unless it was already on RBI's list, and from 28 January 2026 existing apps had to be listed to stay. So a lending app that is missing from Google Play in late 2026 has either been removed, never applied, or can't show a regulated lender.
Testing a loan app in five minutes
- Open the app's store listing and find the lender's name under About this app. No name, no deal.
- Check that the lender appears in RBI's list of registered NBFCs, or is a bank you recognise.
- On rbi.org.in, open Citizen's Corner and the list titled "DLA's deployed by Regulated Entities". The app and lender should appear together.
- Visit the lender's own website. It should name the app and publish a grievance officer.
- Read the Key Fact Statement before you accept any offer, and decline if it's missing.
RBI says it publishes the list exactly as lenders report it, so treat it as a strong first check rather than a guarantee.
Already borrowed through an app like this?
Collect your evidence first
Take screenshots of the loan screen, the amount that actually reached your bank, the repayment demanded and the due date. Note the UTR number of every payment, the UPI IDs or account numbers you paid, and the phone numbers that called you. Export chats before an app or a number disappears.
If you paid a fee and got no loan
Report it the same day on the 1930 helpline or at cybercrime.gov.in. Quick reports give police and banks the best chance of holding money before it moves on. Tell your bank too, and change your UPI PIN if you shared any details.
If you're being threatened
Don't make payments under pressure to personal accounts. File the app on RBI's Sachet portal, which RBI set up for complaints about unauthorised financial activity, and go to your local police station with your evidence. If the app had your contact list, warn family and close friends before anyone else reaches them. If the stress feels too heavy, the free Tele-MANAS helpline on 14416 is there to talk.
Regulated loan apps with published referral rules
If a referral reward is what brought you here, look at apps whose lender and terms are public. KreditBee lends through its group NBFC, Money View pays its reward for a UPI payment, and FatakPay lends through FDPL Finance, an RBI-registered NBFC. Browse every loan app referral code, or read what a referral code is.
Whichever app you pick, borrow only from an RBI-registered lender or its partner, compare the full cost including the processing fee and GST, and never take a loan just to earn a reward.
Q: Is Boost Loan a real loan company?
We couldn't find one. A real lender in India is a bank, an RBI-registered NBFC or a state-licensed moneylender, and its app names that entity. No such entity names an app called Boost Loan, and we found no company registration, office address or grievance officer published under the name. An app can still exist and send money, but nobody regulated answers for it.
Q: Who lends the money in the Boost Loan app?
No lender is named anywhere we could check. That alone breaks RBI's rule, set out in its December 2020 caution, that a lending platform working for a bank or NBFC must tell you the lender's name before you borrow. If an app won't say who is lending, you can't verify the interest, the fees or how your data will be used.
Q: Has RBI approved the Boost Loan app?
RBI doesn't approve apps one by one. It regulates lenders, and since July 2025 it has published the apps those lenders report to it. So the useful question is whether a regulated bank or NBFC lists the app as its own. For Boost Loan we found no such link, and anyone telling you it's 'RBI approved' should show you the lender's name.
Q: Can I download Boost Loan from Google Play?
Not in India, as of 15 November 2026. Searching Google Play for 'boost loan', 'boost loan app' and 'boostloan' brought up only other lenders such as KreditBee, mPokket and Fibe. An older app called BOOST LOANS, package com.boostme.todayx, was removed from Google Play in November 2020, and its listing page now returns an error.
Q: Is Boost Loan the same as MobiKwik Boost?
No. In 2018 MobiKwik launched Boost as an instant-loan feature inside its own wallet app, for existing MobiKwik users. It wasn't a separate app called Boost Loan, and we found no referral code linked to it. If you want MobiKwik's credit products, use the official MobiKwik app and read the lender details it shows before applying.
Q: Why do some loan apps spread only as APK files?
Because Google Play now screens lending apps. Google Play requires personal loan apps in India to appear on RBI's list of digital lending apps and to name every partner bank or NBFC in their description. An app that can't meet those rules has to reach people another way, usually through download links in chats, ads and videos.
Q: What phone permissions should a loan app never need?
Your contact list, call logs, photo gallery, files and media. RBI's digital lending rules bar regulated apps from reading them. A genuine app may ask once for the camera, microphone or location to complete KYC, and only with your consent. If a loan app refuses to work until you share your contacts, treat that as a reason to walk away.
Q: A loan app is threatening to message my contacts. What should I do?
Don't pay into personal UPI IDs or bank accounts under pressure. Save every message, call recording and payment receipt, then complain on 1930 or at cybercrime.gov.in, and at your local police station if you're threatened. Tell close friends and family that fake messages may arrive. If the stress gets heavy, the free Tele-MANAS helpline on 14416 can help.
Q: Can a lender charge me fees that weren't disclosed?
Not a regulated one. Under RBI's digital lending rules you get a Key Fact Statement before you sign, showing the annual percentage rate, every fee and the cooling-off period. A charge that isn't in that statement can't be collected later. An unidentified app gives you no such statement, so there's nothing to hold it to.
Q: Why do YouTube videos share Boost Loan referral codes?
Because the person sharing usually earns when viewers sign up. A video can show an app paying out once and still tell you nothing about who runs it, what the loan really costs or what happens to your data. Before trusting any loan app featured in a video, look for a named bank or NBFC and check it yourself.
Q: Does a referral code make a loan app any safer?
No. A referral code only links your account to the person who invited you, so they can collect a reward. It doesn't change who lends to you, how much interest you pay or which permissions the app takes. A code from a friend you trust on an unverified app carries exactly the same risk as signing up without one.
Q: What does the person who shares a Boost Loan code get?
We couldn't find out, because no lender has published referral terms for an app with this name. On regulated apps the reward is written down: KreditBee, for example, lists its points on an official Refer & Earn page. When no terms exist, there's no way to know what was promised, or whether anyone will honour it.
Q: Can a referral code raise my limit on an instant loan app?
It can't on any app we've reviewed. Loan limits and interest rates come from the lender's check of your income, credit history and KYC, not from a code. Anyone selling a 'special' code that promises a bigger limit, faster approval or zero interest is either mistaken or trying to sell you something.
Q: Is it a problem to post my own code for an unregistered loan app?
It can be. You'd be bringing people to a lender nobody can identify, and some of them may end up with costly loans or harassment. If you want to earn from referrals, share codes for regulated apps whose lender and reward terms are public.
Q: What do people mean by a 'Boost Loan APK referral code'?
It's a code for a version of the app installed from a download link instead of a store. That combination, a sideloaded file plus a code, is the riskiest way to get a loan app, because neither Google nor a regulated lender stands behind the file. We don't share APK links or codes for apps like this.
Q: Which loan apps have published referral rules?
On our site, KreditBee pays points through its group NBFC, Money View pays Mcoins for a UPI payment rather than a loan, and mPokket uses mCoins. Each names its lender. See all loan app referral codes and compare costs before you borrow anywhere.
Q: Should I take a small loan just to get a referral reward?
No. Even a small loan from a regulated lender carries interest, a processing fee and GST, and a late payment can dent your credit score for years. Referral rewards on loan apps are usually a few hundred rupees per friend at most. Borrow only when you need the money and can repay it from your income.
Q: Someone asked for my OTP to 'activate' a referral code. Is that normal?
No. Applying a referral code never needs anyone else to see your OTP, UPI PIN or Aadhaar OTP. With those, a fraudster can take over your account or move money from it. Don't share them, end the conversation, and report the number on 1930 or at cybercrime.gov.in if you've already shared something.
Boost Loan offer terms to know
- RBI's caution of 23 December 2020 says only banks, RBI-registered NBFCs and entities regulated by state governments under laws such as money-lending acts can lend to the public.
- In the same release, RBI said apps that lend for a bank or NBFC must tell customers that lender's name up front.
- Under RBI's Digital Lending Directions of 8 May 2025, lenders report their apps to RBI, which has published them in a public directory since 1 July 2025. RBI lists them as reported and doesn't verify the entries.
- Google Play has required new personal loan apps in India to be on RBI's list since 30 October 2025, and existing ones since 28 January 2026.
- Regulated lending apps may not read your contacts, call logs, files or media. One-time camera, microphone or location access is allowed for onboarding or KYC, with your consent.
- The government told the Lok Sabha in December 2025 that MeitY had blocked 87 illegal loan apps under Section 69A of the IT Act, 2000.
Boost Loan Referral Code: quick FAQs
Do you have a Boost Loan referral code?
We don't share one. We found no RBI-regulated lender behind any app called Boost Loan, so we don't send readers to it.
Can I get a Boost Loan referral code free today?
No code we can recommend. A 'free today' code doesn't change who is lending or what the loan costs, and no one has published referral terms for this app.
Does the Boost Loan APK referral code work?
We don't test or share codes for sideloaded loan apps. Don't install a loan app from an APK link at all.
Is there a Boost Loan referral code for India in 2026?
No verified one. There's no Boost Loan app on Google Play in India, and no bank or NBFC claims it as its app.
Is the Boost Loan app safe?
We can't call it safe. It names no regulated lender, which RBI says every lending platform must do up front.
Where do I complain about a fake loan app?
Call 1930 or file at cybercrime.gov.in, and report the app on RBI's Sachet portal. Go to the police if you're being threatened.
Which loan apps pay real referral rewards?
Regulated apps such as KreditBee, Money View and mPokket publish their referral rules and name their lenders. Never borrow just for the reward.
Written by Recharge n Deals Team
We sign up for every app we list, test the code ourselves and recheck it when the offer changes. Read how we test codes. Code not working? Tell us and we'll recheck it.
Disclaimer: Boost Loan is a trademark of its owner. We are not affiliated with Boost Loan. Offers are set by Boost Loan and can change at any time; check the app before you sign up.